The First-Time Buyer’s Guide to Starter Homes in Potrero Hill
Starter homes in Potrero Hill, a neighborhood on San Francisco's east side, are most often condos, townhomes, and compact attached residences, while detached homes generally require a higher budget. A successful first purchase starts with a payment-first plan that accounts for financing, property taxes, HOA dues, insurance, condition, and long-term flexibility.
Potrero Hill Starter Home Market Overview
Potrero Hill starter-home options are defined more by property type, monthly carrying costs, and condition than by one neighborhood-wide entry price.
- Entry-level choices commonly include condos, townhomes, tenancy-in-common properties, and smaller attached homes.
- Detached starter homes are limited and can command a premium for private outdoor space, parking, and flexible layouts.
- Well-priced homes with strong natural light, practical storage, outdoor access, and transit convenience can attract more attention.
- Days on market, sale-to-list outcomes, and available inventory can vary considerably by building, condition, HOA financial health, and pricing strategy.
What the Potrero Hill First-Time Buyer Market Looks Like Right Now
Potrero Hill remains a selective market for first-time buyers because the neighborhood has limited housing supply and a wide range of ownership formats. Condos and townhomes can create a more manageable entry point than detached homes, although buyers should compare HOA dues, reserve funding, insurance coverage, and building rules alongside the purchase price.
Citywide, the condominium segment has become more competitive. In August 2026, San Francisco's median condo sale price was about $1.23 million, up roughly 22% from a year earlier, and about 54% of condo sales closed above list price (MLS-reported sales). That does not set a price for any Potrero Hill unit, but it signals that well-priced attached homes are drawing more competition than they did a year ago.
Competition tends to be strongest for homes that combine functional layouts with features that support daily life, such as parking, laundry, natural light, storage, and usable outdoor space. Homes with deferred maintenance, unusual floor plans, or high recurring costs may offer more time for comparison.
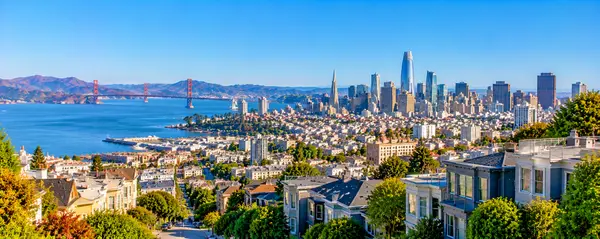
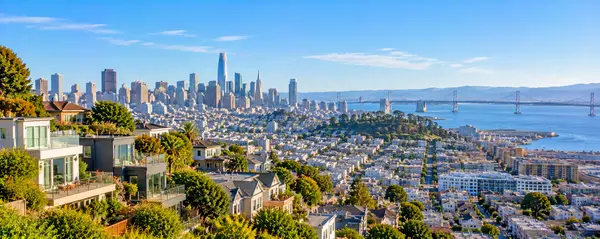
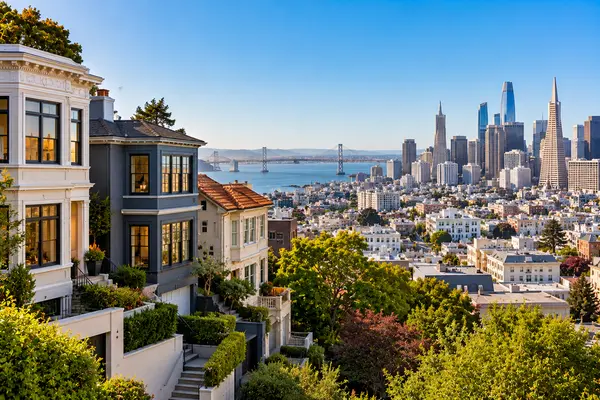
The most useful comparison is often property-specific rather than neighborhood-wide. Reviewing the neighborhood's streets and housing mix alongside disclosures, comparable sales, ownership costs, and commute patterns helps buyers evaluate whether a home fits both current needs and future resale expectations.
Is Potrero Hill Accessible for First-Time Home Buyers Today?
Potrero Hill can be accessible to first-time buyers who focus on attached-home options and set their budget around the full monthly payment.
- Entry-level detached homes are limited, so condos, townhomes, and smaller attached properties often provide more realistic starting points.
- Marketing time can differ based on condition, price positioning, HOA obligations, parking, and outdoor space.
- Offer competition is generally more pronounced for homes with sound maintenance records, practical layouts, and manageable monthly costs.
- Buyers beginning their search today should set a firm payment ceiling, compare ownership structures carefully, and be ready to act when a suitable property appears.
Step 1: Smart Financial Planning for First-Time Buyers
A realistic Potrero Hill purchase budget begins with a monthly payment you can sustain comfortably, not simply the highest amount a lender may approve. Start with stable income, recurring debts, savings goals, moving expenses, and a reserve for homeownership costs that arrive after closing.
Down payment strategy should balance upfront cash with the need to retain reserves. As of October 2026, qualified FHA borrowers may be able to put down as little as 3.5%, subject to FHA and lender requirements. Conventional loan down-payment options can range from lower-down-payment programs to 10% or 20%, depending on credit, property type, loan limits, and long-term plans. A larger down payment can reduce the loan balance and monthly payment, but it should not leave you without funds for repairs, moving, or unexpected costs.
Loan limits matter in a high-cost market. For 2026, the one-unit conforming and FHA loan limit in San Francisco County is $1,249,125. Loan amounts above that generally require jumbo financing, which can carry different down payment, reserve, and qualification requirements. Knowing where your loan amount falls relative to that line helps narrow the right price range early.
Property taxes belong in every payment estimate. Under California's Proposition 13 framework, the base property-tax rate is 1%, with voter-approved debt and local assessments added on top. In San Francisco, the combined secured property tax rate for fiscal year 2026-27 is 1.18162182% of assessed value (San Francisco Treasurer & Tax Collector), and a purchase is generally reassessed at the price you pay. For condos and townhomes, also account for HOA dues, homeowners insurance, potential mortgage insurance, utilities, and a maintenance reserve.
Assistance may be available for qualified first-time buyers based on household income, property eligibility, education requirements, occupancy rules, and program funding. San Francisco's Downpayment Assistance Loan Program (DALP) offers a deferred, no-monthly-payment second loan for eligible buyers of market-rate primary residences, repaid at sale with a share of appreciation. City materials have listed maximum loan amounts ranging from $375,000 to $500,000 depending on the program round and funding source, so buyers should confirm the current cap and application window with the Mayor's Office of Housing and Community Development. State programs through CalHFA may offer additional options for eligible borrowers. The site's first-time buyer guidance covers how these pieces fit together.
Estimated Monthly Cost for Starter Homes in Potrero Hill
Monthly costs should be evaluated as a complete ownership picture rather than as a purchase price alone. A buyer comparing starter homes should model the mortgage payment using a lender-provided rate and down payment scenario, then add property taxes, homeowners insurance, HOA dues where applicable, utilities, and a reserve for maintenance. Running each property through the same payment calculator with identical assumptions makes side-by-side comparisons much clearer.
For attached homes, HOA dues can materially change the monthly total even when two properties have similar prices. For detached homes, lower or no HOA dues can be offset by direct responsibility for exterior maintenance, roofing, drainage, landscaping, and insurance needs. A payment comparison is most useful when every property is evaluated using the same financing assumptions and cash-reserve target.
Step 2: Securing Pre-Approval and Exploring First-Time Buyer Programs
Pre-approval is essential because it documents your financing position and establishes a credible purchase range before you begin writing offers. A lender reviews income, assets, credit, recurring debts, employment history, and the proposed loan structure to clarify the payment and cash-to-close requirements.
Buyers should prepare recent pay stubs, tax returns, bank statements, identification, and documentation for gift funds or other income sources. Self-employed buyers, buyers with variable compensation, and buyers using assistance programs may need additional documentation and should allow time for review. DALP applicants, for example, generally need a recent pre-approval letter and completed homebuyer education before applying.
Conventional loans can offer flexibility for qualified buyers. FHA financing can support lower down payment options for eligible borrowers. VA financing can provide important benefits for eligible service members, veterans, and surviving spouses. The appropriate loan depends on the buyer's finances, the property type, and the payment that remains sustainable after closing.
A complete pre-approval also helps buyers assess an offer before submitting it. It confirms that the proposed price, down payment, closing funds, and projected monthly payment work together as one plan.
Step 3: Where to Look for Starter Homes in Potrero Hill
Potrero Hill offers several distinct living environments, and the right fit depends on a buyer's space needs, commute, maintenance preferences, and ownership priorities.
Homes closer to the neighborhood's commercial areas along 18th and 20th Streets can appeal to buyers who value walkability, dining, and convenient access to the rest of San Francisco. These locations may include condos and smaller attached homes that reduce exterior maintenance responsibilities.
Quieter residential streets can suit buyers looking for a more traditional neighborhood setting, larger layouts, private outdoor areas, or detached-home potential. These properties may require a higher entry budget and more direct responsibility for systems, upkeep, and insurance.
Multifamily buildings can work well for buyers who prioritize efficient layouts, predictable exterior maintenance, and lower day-to-day property responsibilities. Buyers who work remotely may place extra value on storage, natural light, a flexible second room, and reliable separation between living and work areas.
Across Potrero Hill, hillside placement, sunlight, stair access, parking conditions, views, and transit connections can change the experience of a property. Touring at different times of day offers a clearer picture than listing photos alone.
Step 4: Evaluating Starter Properties for Long-Term Value
A starter home should be evaluated for both present comfort and future marketability.
- Prioritize structural condition, water management, roof age, electrical capacity, plumbing, and heating systems before cosmetic finishes.
- Test whether the layout supports daily routines, including storage, work-from-home needs, stairs, laundry, natural light, and possible household changes.
- Review HOA documents for reserve funding, insurance coverage, planned projects, rental restrictions, and fee history when considering attached homes.
- Consider resale appeal by assessing location, parking, outdoor space, functional layout, condition, and future buyer demand.
- Compare recently sold homes with similar size, condition, ownership structure, and location, then note which features affect total ownership value.
If there is a chance you will rent the home out after moving up, it helps to understand early how Potrero Hill performs as a long-term hold, including the city's rent rules and the building issues that affect future value.
Step 5: Crafting a Winning Offer on Your First Home
A competitive Potrero Hill offer is complete, financially grounded, and aligned with the buyer's actual limits. Sellers typically evaluate more than price, including financing strength, earnest money, requested concessions, contingency timelines, closing date, and the overall reliability of the transaction plan.
Before writing an offer, confirm the funds available for the down payment, closing costs, and earnest money deposit. Review how the proposed price, any seller credits, and the projected payment affect the loan structure. A clear offer package can reduce uncertainty without requiring a buyer to accept terms that create unnecessary financial pressure.
Appraisal and inspection contingencies should reflect the property, financing plan, disclosures, and your comfort level with risk. Buyers need adequate time to review documents, complete due diligence, and satisfy loan conditions. The strongest timeline is one that is both competitive and realistic.
Avoid raising the price beyond your planned ceiling simply to win. A starter home should create a foundation for future ownership rather than ongoing strain on monthly finances.
The most common mistake is focusing only on the offer price and overlooking the full terms of the purchase. Avoid it by reviewing the projected payment, cash to close, timelines, property condition, and ownership costs before submitting an offer.
Step 6: Home Inspections, Appraisal, and Closing Day in Potrero Hill
Closing requires a careful review of the home's condition, value support, ownership documents, and final loan requirements. Buyers commonly arrange a general inspection and may add specialized reviews for the sewer line, roof, foundation, or major systems identified in disclosures or during the initial review.
The lender's appraisal helps determine whether the property supports the agreed loan amount. If the appraised value differs from the contract price, the parties may need to revisit financing, price, or the buyer's cash contribution. A title search reviews the ownership record for liens, easements, and other matters that should be resolved before closing.
Closing costs depend on the transaction, loan structure, and negotiated terms. Request a detailed loan estimate early, then compare it with the final closing disclosure before signing. Keep financial activity stable during escrow, avoid taking on new debt, and respond promptly to lender requests.
Starter Townhomes vs. Single-Family Starter Homes in Potrero Hill
| Consideration | Starter Townhome | Single-Family Starter Home |
|---|---|---|
| Typical Price Point | Can offer a lower entry point than a comparable detached home | Often carries a premium for privacy and land |
| Exterior Maintenance Responsibility | Usually shared through an HOA structure | Usually handled directly by the owner |
| HOA Fee Expectations | Common, with costs tied to services and reserve funding | Less common unless within a planned community |
| Private Yard Space | May include patios, decks, or limited outdoor areas | More likely to include exclusive outdoor space |
| Resale Demand | Can be strong when layout, location, and HOA health are compelling | Often broad for functional layouts and usable outdoor space |
| Financing Considerations | HOA documents and project eligibility can affect financing | Property condition and insurance needs can be key factors |
| Appreciation Potential | Depends on location, condition, and building management | Depends on location, condition, lot utility, and buyer demand |
For first-time buyers comparing starter homes in Potrero Hill, the strongest starting point is a payment-first search plan that accounts for property type, HOA obligations, condition, and future resale needs.
Ready to Start Your Potrero Hill Search?
J. Ramon Estevez is a licensed REALTOR® who works directly with first-time buyers in San Francisco, with no handoff to a team partway through. He explains financing, disclosures, and contingencies plainly, reviews the full disclosure and HOA package before an offer goes in, and structures offers around what the seller is trying to solve for. To talk through your budget and what Potrero Hill can offer at that price, call or text (415) 697-0928, email ramon@ramonestevez.com, or reach out here. You can also browse current listings to get a feel for what is available.
Frequently Asked Questions: Buying a Starter Home in Potrero Hill
What is the average price of a starter home in Potrero Hill?
Starter-home pricing in Potrero Hill varies widely by property type, size, condition, ownership structure, parking, and HOA obligations. For citywide context, San Francisco's median condo sale price was about $1.23 million in August 2026. Condos, townhomes, and smaller attached homes generally provide a different entry point than detached homes, so buyers should compare similar properties instead of relying on one figure.
How much down payment do first-time buyers need for a home in Potrero Hill?
As of October 2026, qualified FHA borrowers may be able to purchase with a 3.5% down payment, subject to FHA and lender requirements. Conventional buyers may consider lower-down-payment options as well as 10% or 20% strategies, depending on credit, loan terms, property type, and reserve goals. Loan amounts above $1,249,125 in San Francisco County generally require jumbo financing.
Are there first-time homebuyer assistance programs available in Potrero Hill?
Eligible buyers may have access to San Francisco and California assistance programs tied to income, occupancy, education, and funding requirements. San Francisco's DALP provides a deferred second loan for qualified market-rate primary-residence buyers, with city materials listing maximums between $375,000 and $500,000 depending on the program round, so the current cap should be confirmed before applying.
Should first-time buyers in Potrero Hill buy a townhome or a single-family house?
A townhome can suit buyers who prefer shared exterior maintenance and defined building responsibilities. A single-family home may provide more privacy and outdoor space, but it can also require a higher initial budget and more direct maintenance planning.
How long should I plan to stay in a starter home before upgrading?
A five-to-seven-year ownership horizon is often used when buyers consider transaction costs and future flexibility. The better decision is to choose a home that can support likely changes in work, household needs, and finances during your expected holding period.
Categories
Recent Posts